B2B calculator 2026: what is left from your invoice
Enter your monthly net invoice revenue and business costs, pick a ZUS variant and the calculator compares the 12% and 8.5% lump-sum tax (ryczałt), the 19% flat tax and the tax scale. Next to it we show an employment contract that costs the employer as much as your invoice.
Lump-sum 12%
PLN 10,223.74take-home a month- ZUS
- PLN 1,927
- Health
- PLN 831
- Tax
- PLN 1,519
Lump-sum 8.5%
PLN 10,666.74take-home a monthMost take-home- ZUS
- PLN 1,927
- Health
- PLN 831
- Tax
- PLN 1,076
Flat 19%
PLN 9,685.32take-home a month- ZUS
- PLN 1,927
- Health
- PLN 616
- Tax
- PLN 2,272
Scale 12/32%
PLN 9,718.23take-home a month- ZUS
- PLN 1,927
- Health
- PLN 1,132
- Tax
- PLN 1,723
Employment contract, same cost
PLN 8,718.80- Gross
- PLN 12,450
- Employer's cost
- PLN 15,000
Take-home = revenue − costs − ZUS − health − tax, monthly average (annual settlement). Employment contract: the gross that costs the employer as much as the invoice; net as a yearly average.
For information only — not a substitute for an accountant. The 12% lump-sum applies to programming (PKWiU 62.01) among others, 8.5% to some other IT services; check the rate for your PKWiU code. B2B has no paid leave or sick pay — include that in your rate.
Business ZUS contributions in 2026
| Variant | Base | Contributions (with sickness) |
|---|---|---|
| Start relief (6 months) — health only | — | PLN 0.00 |
| Preferential ZUS (24 months) | PLN 1,441.80 | PLN 456.18 |
| Mały ZUS Plus (approximation) | PLN 1,441.80 – PLN 5,652.00 | — |
| Full ZUS | PLN 5,652.00 | PLN 1,926.76 |
B2B health insurance in 2026
- Scale 12/32%
Scale: 9% of income, at least PLN 432.54 a month.
- Flat 19%
Flat: 4.9% of income, at least PLN 432.54; up to PLN 14,100.00 a year is deductible from income.
- Lump-sum 12% / Lump-sum 8.5%
Lump-sum: a fixed amount by annual revenue: up to PLN 60,000 — PLN 498.35, up to PLN 300,000 — PLN 830.58, above — PLN 1,495.04 a month; half of it reduces the taxed revenue.
B2B or employment contract in a minute
B2B or an employment contract? What changes for the same amount
60 s · Polish voice-over · Polish captions, English subtitles
Video transcript
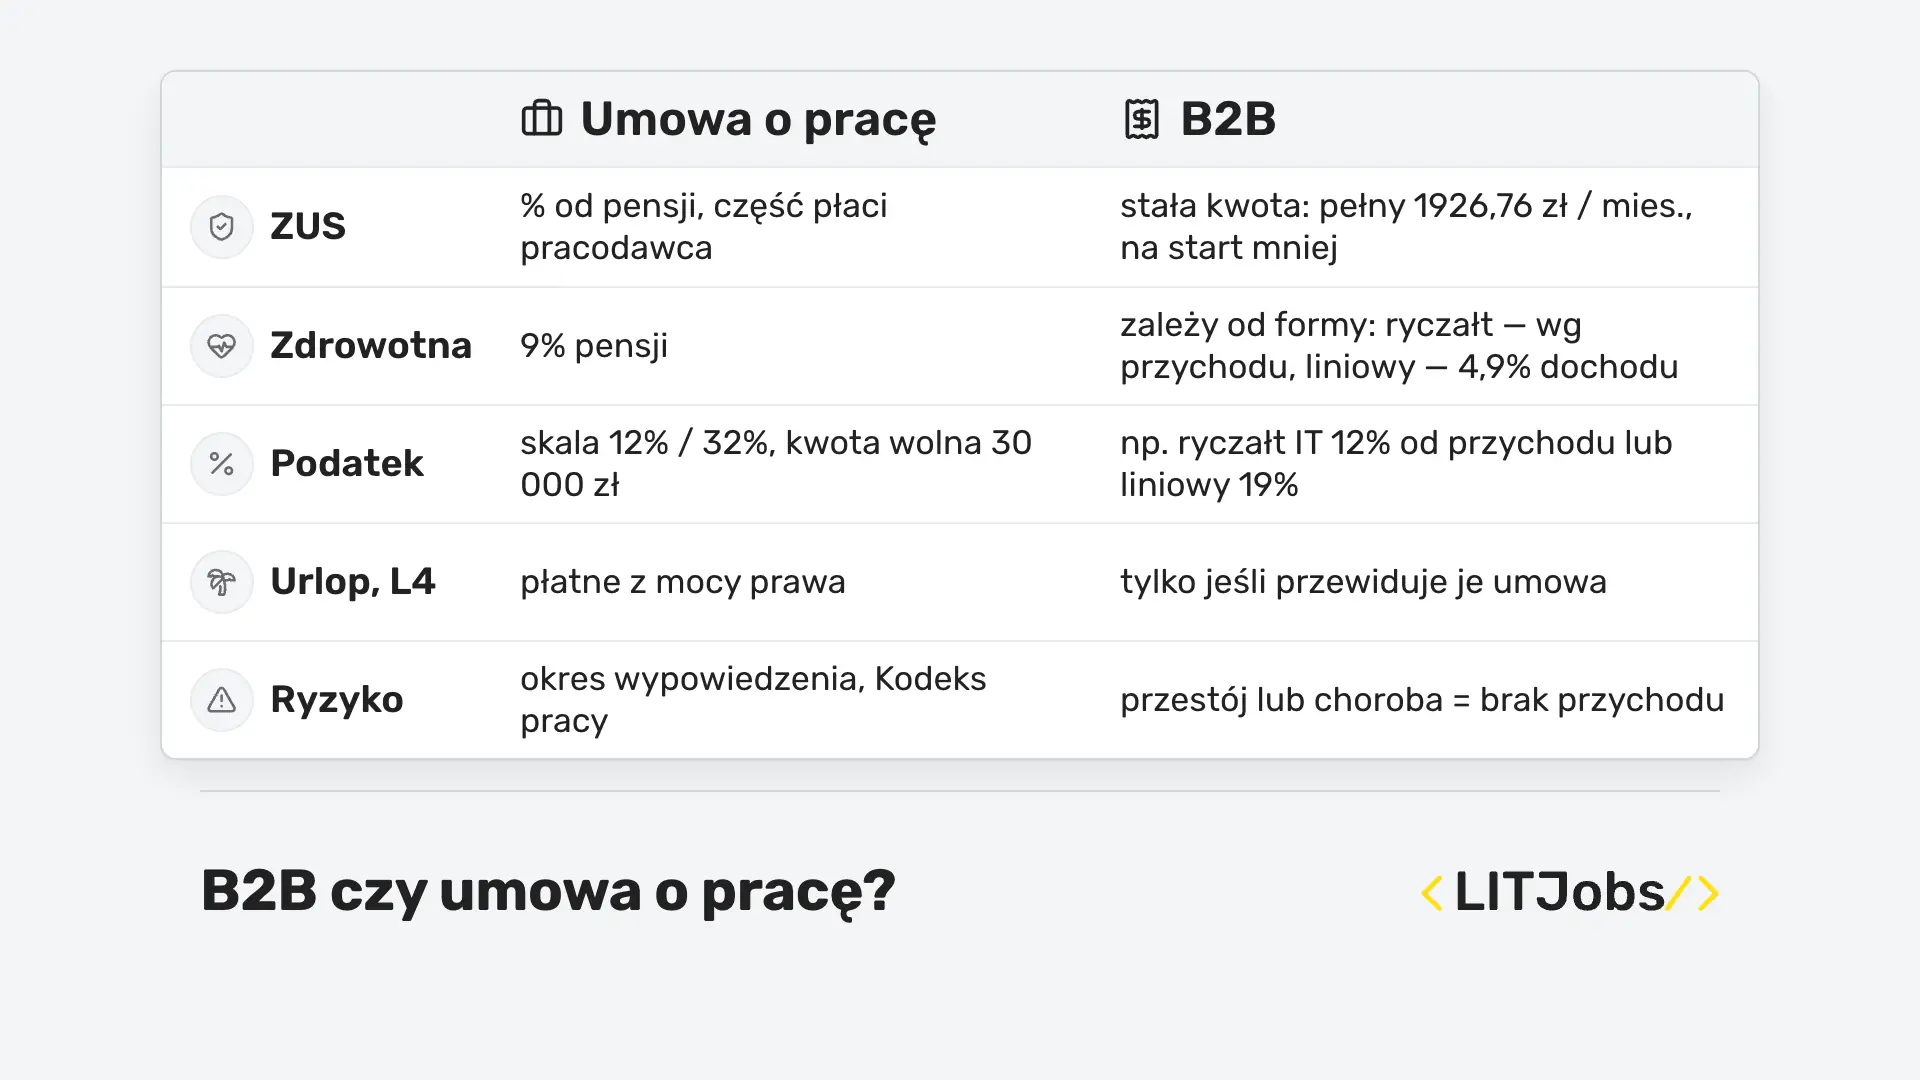
The same amount: employment contract or B2B? What changes is what's left of it and what comes with it. Social security (ZUS): on a contract, a percentage of the salary. On B2B a fixed amount — the full rate is PLN 1,926.76 a month. Health contribution: 9% on a contract; on B2B it depends on the tax form. Tax: a contract uses the 12/32% scale; B2B e.g. 12% lump-sum tax or the 19% flat tax. Paid leave and sick pay: guaranteed on a contract; on B2B only if the agreement provides them. Risk: on B2B, downtime or illness means no income. For the same amount, B2B usually leaves more in your pocket. A contract gives you paid leave, sick pay and stability instead. Compare annual net income, not just the rate. Work out your own case in the B2B / employment calculator. Try the calculator.
Open the full salary calculator
Frequently asked questions
What pays off more in IT: the 12% lump-sum or the flat tax?
With low business costs the 12% lump-sum usually leaves more, because the tax is a low rate on revenue and the health contribution is fixed. The flat tax pays off with high costs (equipment, subcontractors) or very high income, where deducting health insurance helps. Enter your own figures — the difference can be several hundred złoty a month.
How much is full ZUS in 2026?
Full business social contributions in 2026 are computed on a PLN 5,652 base. With voluntary sickness insurance and the Labour Fund that is PLN 1,926.76 a month. Health insurance comes on top and depends on the form of taxation.
Which B2B invoice matches a salary on an employment contract?
Compare at the same cost for the company: a PLN 12,048 net invoice costs the employer roughly as much as a PLN 10,000 gross job. B2B usually leaves more money, but without paid leave, sick pay and Labour Code protection — price those into your rate.
When does the 8.5% lump-sum apply instead of 12%?
The 12% rate covers programming and IT consulting (e.g. PKWiU 62.01 and 62.02). Some other IT services, such as parts of software-related and data processing services, may be taxed at 8.5%. The rate follows the PKWiU code of the service — if in doubt, ask KIS for a ruling.